Washington & Oregon • General contractors & specialty trades
Contractor Insurance in Washington & Oregon
Liability, bonds, vehicles and equipment. Get a coordinated insurance review with Jesus Galvan, built around the work you do and the requirements you need to meet.
English / Español · Jesus is licensed in all 50 states.For the people who build and keep projects moving
Coverage built around your trade.
A contractor’s insurance needs go beyond a certificate. BearStar helps Washington and Oregon businesses review their operations, crews, vehicles, equipment and contract requirements together.
General Contractors
Residential and commercial work, remodeling and project coordination. Review subcontractor use, jobsite exposures and the limits requested by owners and lenders.
Specialty Trades
Coverage conversations for electrical, plumbing, HVAC, painting, drywall, flooring, concrete and other trades, based on the actual work performed.
Growing Businesses
Adding employees, trucks, equipment or work in another state? Revisit your insurance as the business changes, before a new exposure becomes a problem.

A broker you can speak to directly
Meet Jesus Galvan
Broker Partner | BearStar Insurance Services
Jesus works with business owners and contractors to understand their operations, identify coverage questions and compare available insurance options. He can help organize the information insurers need and review the documentation requested by owners and general contractors.
Jesus is licensed in all 50 states, so he can also assist contractors working outside Washington and Oregon. He works with clients in English and Spanish, backed by a BearStar team with over 100 years of combined insurance experience.
888-601-0088 ext. 108Jesus@bearstarins.com
Meet the BearStar team →One conversation. A coordinated coverage review.
Insurance for your business and your next job.
Tell Jesus what you build, repair or install, where you work and what your contracts require. The right mix of coverage depends on your trade, employees, subcontractors, vehicles and projects.
General Liability
Review protection for covered third-party injury and property damage claims, along with completed operations and contract-required endorsements. Limits and exclusions should reflect the work you perform.
Contractor Bonds
Discuss surety bonds for applicable registration, licensing, bid, performance or payment requirements. Bond type and amount depend on your classification and the obligation involved.
Commercial Auto
Review business vehicle insurance for trucks and vans, listed drivers, trailers and usage. Hired and non-owned auto exposures may also need attention.
Tools & Equipment
Consider owned and rented tools, mobile equipment and property at the shop, in transit or on a jobsite. Ask about theft conditions, scheduling, limits and deductibles.
Employee Coverages
Discuss Oregon workers’ compensation and employer liability needs. Washington’s state-run workers’ compensation system requires a different approach; see the state guidance below.
Project & Excess Coverage
Consider builders risk, umbrella or excess liability, and professional or pollution coverage when the project or scope of work calls for them.
Regional requirements deserve a closer look
Washington and Oregon are different.
Registration and licensing requirements are a starting point. The insurance limits and endorsements in a job contract may go further.
Washington contractors
Washington L&I contractor registration requires liability insurance and a surety bond or approved assignment of savings. Review the exact business name, contractor classification and certificate requirements alongside your project contracts.
Washington workers’ compensation is provided through L&I or approved self-insurance. Washington does not permit private workers’ compensation coverage for its state system. Jesus can help you review related coverage questions and direct you to the appropriate state resources.
Washington L&I contractor registration →
Washington workers’ compensation guidance →
Oregon contractors
Oregon CCB liability insurance and bond requirements depend on the contractor’s endorsement. Your residential or commercial classification matters, as does the work you actually perform.
Contractors hiring employees generally need workers’ compensation coverage. Jesus can review your endorsement, liability coverage, bond, employee exposures, vehicles and insurance requirements together.
Working in other states too? Jesus is licensed in all 50 states and can assist with insurance needs beyond Washington and Oregon. Tell him every state where your business operates so the coverage review reflects your footprint.
Clearer requirements. Better preparation.
Get the insurance details sorted before the next job.
Send Jesus the insurance section of your contract or a request from an owner or general contractor. He can help review requested limits, additional insured wording, primary and noncontributory status, waivers of subrogation and certificate needs.
Certificates show evidence of coverage; they do not replace policy terms or add coverage by themselves. Requested endorsements depend on the policy and insurer approval.
For a broader overview, explore BearStar’s contractor insurance services. Planning a $5M–$100M apartment, high-rise or mixed-use development? See our large-project construction insurance page.
What to have ready
- Your business: legal name, trade, license or registration and states where you work.
- Your operations: work performed, estimated revenue, payroll, employees and subcontractor use.
- Your property: vehicles, drivers, tools and equipment that need coverage.
- Your current program: policies, renewal date and available loss history.
- Your deadline: contract, bond or certificate requirements and the date coverage is needed.
Start with what you have. Jesus will help identify what is still needed for the next step.
Start Your Coverage ReviewWashington & Oregon contractor insurance FAQs
Answers before you get started.
What insurance does a Washington contractor need?
Contractor registration includes liability insurance and a bond or approved assignment of savings. Your trade, employees, vehicles and project contracts may create additional requirements. Washington workers’ compensation is handled through L&I or approved self-insurance.
What insurance does an Oregon contractor need?
Oregon CCB requirements depend on your endorsement, including liability coverage and a contractor bond. Employee exposures may require workers’ compensation. Review your actual classification and work before selecting limits or applying for a bond.
Is a contractor bond the same as liability insurance?
No. A bond supports a specific obligation, such as licensing or contract performance. General liability addresses covered third-party injury or property damage claims. One does not replace the other.
How much does contractor insurance cost?
Pricing depends on your trade, work performed, revenue, payroll, claims history, limits, deductibles and other underwriting factors. Jesus can help organize your business information and compare available options.
Can Jesus help if we work outside Washington or Oregon?
Yes. Jesus is licensed in all 50 states and can also assist with insurance needs in other states. Let him know all operating locations, including work across state lines.
Can we discuss our coverage in Spanish?
Yes. Jesus works with clients in English and Spanish. Call 888-601-0088 ext. 108 or mention your preferred language in the inquiry form.
Washington & Oregon contractor coverage
Talk to Jesus about your next step.
Whether you are starting a business, renewing coverage, adding crews or reviewing a new contract, begin with a conversation about the work you do.
- General contractors and specialty trades
- Liability, bonds, vehicles, equipment and project needs
- English and Spanish service
Contact Jesus Galvan directly
888-601-0088 ext. 108
Jesus@bearstarins.com
Focused on Washington and Oregon contractors. Licensed in all 50 states to assist with your business elsewhere, too.
Tell Jesus about your business
Coverage descriptions are general. Availability, limits, deductibles, exclusions and claim response depend on underwriting and the policy issued. State requirements depend on the work and classification. Requesting a review does not bind coverage.
Photography credit
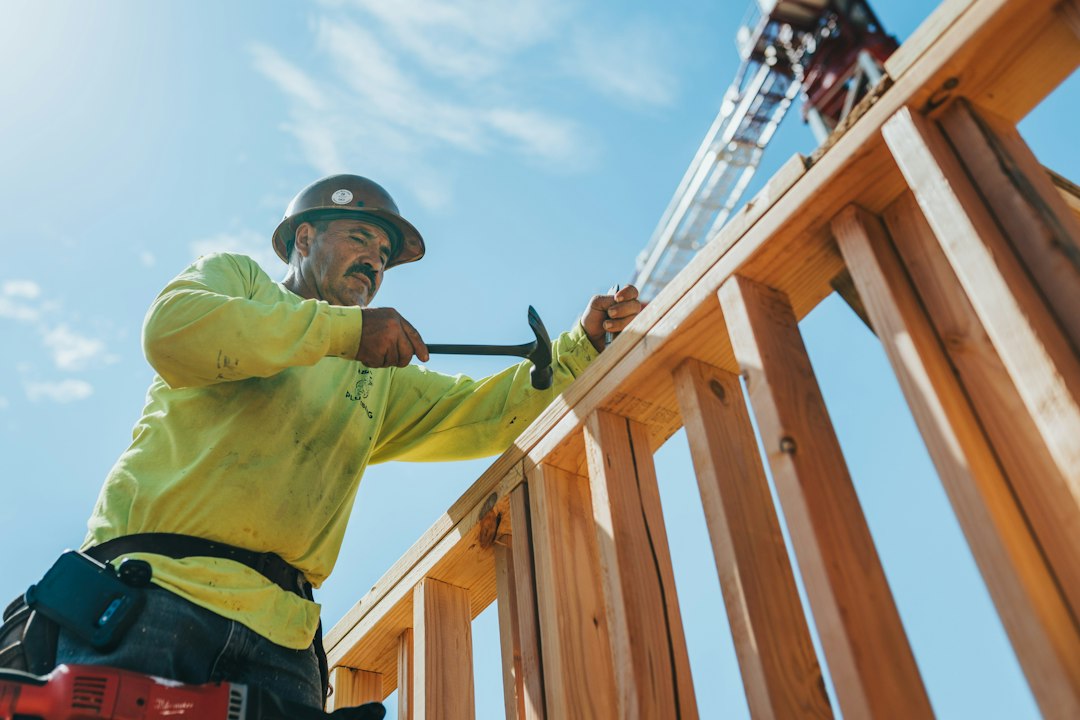
Illustrative contractor photography by Josh Olalde on Unsplash.