California construction insurance • $5M–$100M projects
Construction Insurance for Multifamily & High-Rise Projects
Builders risk, project liability and risk guidance for $5M–$100M apartment, high-rise and mixed-use developments.
Serving California owners, developers & general contractors.Construction insurance for complex developments
Built around what you build.
A large building project brings owners, lenders, contractors and subcontractors together. BearStar helps coordinate the insurance conversation around your construction value, schedule, contracts and project exposures.
Multifamily & Apartments
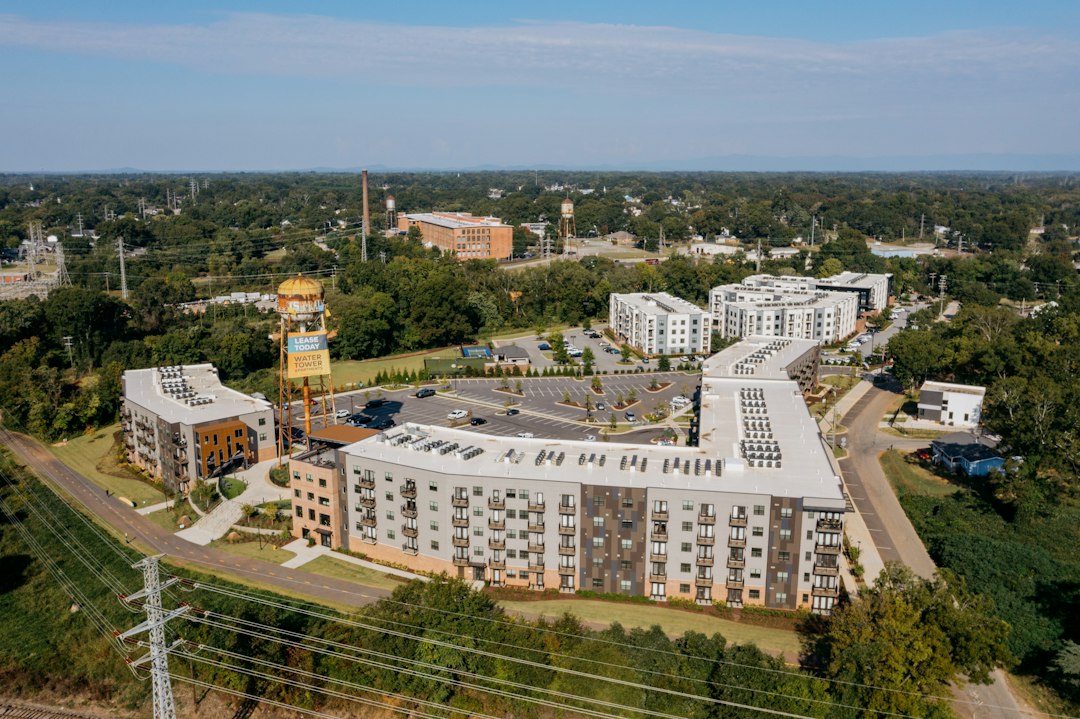
Construction insurance for new apartment communities, multifamily developments and substantial renovations, with attention to phased completion and the transition to occupancy.
High-Rise Developments
Insurance planning for vertical construction, including project values, neighboring property, water damage exposures and the liability limits required by owners and lenders.
Mixed-Use Projects
A coordinated review for developments combining residential space, retail, offices or other uses, including multiple insured entities and changing exposures as work progresses.
Experience you can speak to
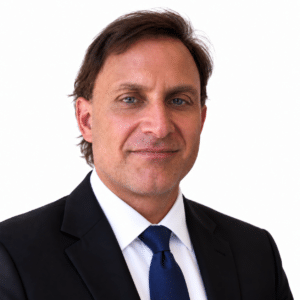
Meet Matt O’Connor
Broker Partner | BearStar Insurance Services
Matt brings commercial insurance experience across brokerage and carrier roles, with a background advising developers, homebuilders and contractors. He is your direct contact for understanding the project, coordinating coverage options and helping address insurance questions as construction moves forward.
Behind that personal relationship is a BearStar team with over 100 years of combined insurance experience, spanning coverage placement, risk management and claims assistance.
888-601-0088 ext. 110Matt@bearstarins.com
Meet the BearStar team →Coverage built around the project
A coordinated approach to project risk.
Commercial construction insurance often involves several policies. We help you review how the proposed coverage fits the work, ownership structure, lender requirements and contractual responsibilities.
Builders Risk Insurance
Also called course of construction insurance, builders risk addresses covered physical loss to the project during construction. Review materials, equipment to be installed, transit, offsite storage, testing and the policy’s completion provisions.
Liability & Excess
Evaluate project and operational general liability, additional insured requirements and completed operations, together with umbrella or excess liability limits appropriate to the development.
Wrap-Up Options
Discuss whether an owner-controlled insurance program (OCIP), contractor-controlled program (CCIP) or traditional insurance structure fits the project. Eligibility, enrollment, exclusions and administration all require review.
Risk & Claims Support
Get help organizing insurance requirements, identifying coverage questions and reporting a claim. Matt can assist with communication and documentation as the insurer evaluates the loss.
Start before the first shovel
Builders risk insurance that reflects your construction plan.
Course of construction coverage should follow the actual project—not just a contract’s insurance checklist. Before work begins, discuss the construction method, full completed value, estimated duration, site protection and anticipated occupancy.
For an apartment or high-rise development, the review may include water intrusion, theft, fire, catastrophe exposures and work beside existing structures. Flood and earthquake require specific attention; do not assume they are included.
Ask about soft costs and delay in completion coverage where available, including the covered-loss trigger, waiting period, limits and documentation requirements. Extensions, changes in value and phased handovers should be addressed before they create a gap.
Planning for a completed rental property? Explore apartment owners insurance. For your broader operations, review our contractor insurance services.
What we need to start a project review
- Project basics: location, use, owner and developer entities, construction type, height and unit count.
- Value and timing: construction budget, target start, estimated completion and any phased occupancy.
- Project team: general contractor, key subcontractors and relevant experience.
- Requirements: lender terms, contracts, requested limits and additional insured provisions.
- Existing information: current coverage, loss history, site plans and protective measures, as available.
You do not need every document to begin. Send the basics through the form below and Matt will help identify the next information needed for a meaningful insurance submission.
Start Your Project ReviewConstruction insurance questions
Plan with a clearer picture.
Is builders risk the same as construction general liability?
No. Builders risk focuses on covered physical loss to the construction project. General liability addresses covered third-party bodily injury or property damage claims, subject to its terms. A construction insurance program may need both, along with other policies for the parties and work involved.
Who should arrange builders risk insurance—the owner or contractor?
The contract and financing arrangements help determine who is responsible. The policy should identify the parties with an insurable interest and address how their interests are protected. Review this before construction starts so the owner, developer, contractor and lender understand the arrangement.
Can you help with $5 million to $100 million projects?
Yes. This service focuses on apartment, high-rise and mixed-use developments in that construction value range. Coverage options depend on the location, construction, schedule, project team, loss history and underwriting. Send Matt the project basics to begin the review.
When should we begin the insurance review?
Start during planning or financing, before signing final insurance requirements or beginning work. Larger and more complex developments may require additional underwriting information, insurer coordination and time to evaluate options.
How much does commercial construction insurance cost?
Pricing depends on the project’s value, location, construction method, duration, protections, coverage limits and deductibles, among other underwriting factors. Matt can help organize the details needed to seek terms. A project-specific review is more useful than a generic rate estimate.
What happens when the project is completed or occupied?
Builders risk policies have specific termination and occupancy provisions. Coordinate the transition to permanent property and liability coverage, including phased occupancy, and review any continuing completed operations requirements before the construction policy ends.
Your next project starts here
Start with a conversation about your next project.
Tell Matt what you are building, where it is located and your estimated construction value. He will help identify the coverage questions and information needed for the next step.
- $5M–$100M apartment, high-rise and mixed-use developments
- Builders risk, project liability and wrap-up options
- Support from planning through claims assistance
Contact Matt O’Connor directly
888-601-0088 ext. 110
Matt@bearstarins.com
Based in Irvine, serving California projects and other states where BearStar and its affiliates are licensed.
Tell Matt about your project
Coverage descriptions are general. Availability, limits, deductibles, exclusions and claim response depend on underwriting and the policy issued. Requesting a review does not bind coverage.
Photography credits
Illustrative project photography, not a portfolio of insured projects. Photos by novila misastra, Alex Reynolds, Zoshua Colah and Margo Evardson on Unsplash.